Roth conversion
Pay the tax now, withdraw tax-free later
Money in a Traditional IRA is taxed when you take it out. Pay that tax now and move it to a Roth, and once the conditions are met, withdrawals come out tax-free. It is not right for everyone, so we start with the numbers.
First call is free · English / 한국어 · CA Lic. #4582405
Pay the tax now,and here is what you gain
Tax-free withdrawals
Once the conditions are met, even the growth comes out untaxed.
Better to inherit
It can pass to your beneficiaries without an income tax bill.
No RMDs
No required withdrawals in your lifetime, so it can keep growing.
No income limit
Under current rules, anyone can convert, whatever they earn.
Traditional vs. Roth
- Going in
- Traditional IRA Tax deduction nowRoth IRA No deduction (after-tax money)
- Coming out
- Traditional IRA Taxed as incomeRoth IRA Contributions and growth tax-free, if conditions are met
- Required withdrawals
- Traditional IRA Start at a set ageRoth IRA None in your lifetime
- Inheritance
- Traditional IRA Taxed when heirs withdrawRoth IRA Passes without income tax
| Traditional IRA | Roth IRA | |
|---|---|---|
| Going in | Tax deduction now | No deduction (after-tax money) |
| Coming out | Taxed as income | Contributions and growth tax-free, if conditions are met |
| Required withdrawals | Start at a set age | None in your lifetime |
| Inheritance | Taxed when heirs withdraw | Passes without income tax |
Which one wins depends on your tax rate now versus later. The Traditional deduction lowers adjusted gross income (AGI), which can matter a lot if you are near an ACA health insurance subsidy threshold.
Who it tends to suit
-
You expect a higher rate later
Pay at today’s lower rate instead of tomorrow’s higher one.
-
You want tax-free retirement income
With no tax on withdrawals, retirement budgeting gets simpler.
-
Your income dipped this year
Converting in a lower-income year can cut the tax bill.
-
You plan to leave it to family
Your beneficiaries can inherit it without an income tax bill.
Run it past your tax advisor
The amount you convert is generally added to that year’s income and taxed. Work through the numbers with your CPA or tax advisor before converting. I do not provide tax advice.
Questions people ask
When do I pay the tax?
The converted amount is added to that year’s income and taxed with it. A large conversion can push you into a higher bracket, so many people convert in pieces over several years.
Can I convert if my income is high?
Under current rules, yes. Conversion has no income limit. Rules can change, so we check again when you are ready.
Does a Roth have required withdrawals?
Not while the owner is alive. There is no RMD pushing you to draw it down.
Can it affect my health insurance subsidy?
It can. A conversion raises your adjusted gross income (AGI), which can change ACA subsidy eligibility. If you are near a threshold, check with your tax advisor first.
When does converting not make sense?
If you expect a lower tax rate in retirement, keeping it Traditional may be better. It also matters where the money to pay the conversion tax will come from.
Related services
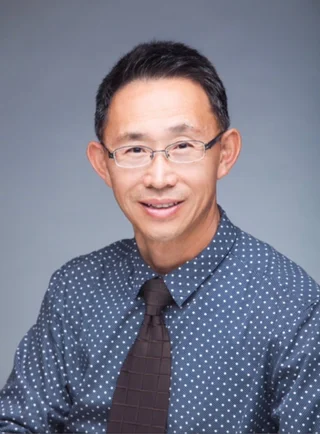
신현인 Sam Shin
Retirement planning specialist · I call you back myself
Book a free call
Leave your name and number and I will get back to you personally.
A call back within one business day
In English or Korean, at a time that suits you.
Carriers compared side by side
The terms on one page, sent to you by email.
Free, with no obligation
Tell me you are not interested and I will stop.
-
Looked after long after you sign
I reach out before maturities and renewals.
Prefer to talk now? (213) 507-2224