LTC checklist
Check before you sign, it changes the outcome
Long-term care terms differ a lot from one product to the next. To get the benefit you expect, in the form you expect, a few things need checking first.
First call is free · English / 한국어 · CA Lic. #4582405
Start with what is covered
Make sure the plan covers the kind of care you would actually want. The support services matter more than people expect when the time comes.
- Home care
- Assisted living
- Adult day care
- Nursing home
- Hospice
- Care coordination
- Caregiver training
- Respite care
- Bed reservation
- Care abroad
What to check before you apply
-
Premium against benefit
Balance a premium you can keep paying for years against a benefit that will cover future costs. Single pay, 10-pay and lifetime pay suit different situations.
-
Elimination period
The wait between qualifying and the money starting. Ninety days is typical, it can range from 0 to 180, and shorter costs more.
-
Inflation protection
Care costs rise fast. An amount that looks generous today can be thin later, so a benefit that grows each year deserves serious thought.
-
Paid-up coverage
If premiums become hard to pay, this keeps a reduced benefit in force instead of losing what you have paid so far.
-
How the benefit is paid
Claiming against receipts, or receiving a set amount. How freely you can use the money is very different.
-
Waiver of premium
Once you start receiving benefits, this stops the premiums, easing the financial load while you are in care.
Coverage, triggers and premiums vary widely by product. All require health underwriting, and the healthier you are, the better the terms.
Complex, but you don’t have to choose alone
I explain what each of these actually means in plain words, then design a plan around your situation and goals. I stay with you from the first question to the policy.
Questions people ask
How long should the elimination period be?
Ninety days is a common choice. Shorter costs more and longer costs less, so a good guide is how long you could cover care from your own savings.
Do I really need inflation protection?
Care costs rise quickly, so an amount that looks generous today may fall short in fifteen years. It does raise the premium, so I show you both sides.
What if I can no longer pay premiums?
If your plan includes paid-up coverage, you can keep a reduced benefit instead of cancelling. Not every product includes it, so check before you apply.
Do I keep paying premiums while I receive care?
With a waiver of premium, you stop paying once benefits begin. This also differs by product.
Will it pay if family members care for me?
Cash indemnity plans have no limits on how the money is used, so they can cover family caregivers. Reimbursement plans offer limited cover for informal caregivers.
Related services
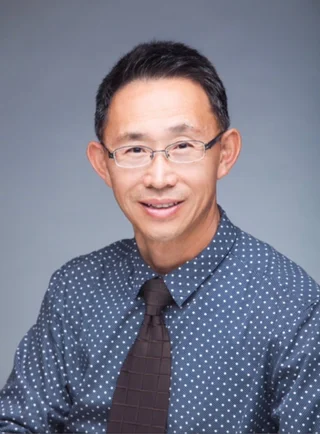
신현인 Sam Shin
Retirement planning specialist · I call you back myself
Book a free call
Leave your name and number and I will get back to you personally.
A call back within one business day
In English or Korean, at a time that suits you.
Carriers compared side by side
The terms on one page, sent to you by email.
Free, with no obligation
Tell me you are not interested and I will stop.
Looked after long after you sign
I reach out before maturities and renewals.
Prefer to talk now? (213) 507-2224