Long-term care
When care is needed, keep it off your family
Long-term care is easy to put off, but by the time you need it, few options are left. Planning while you are healthy lowers the cost and widens the choices.
First call is free · English / 한국어 · CA Lic. #4582405
For people who want to decidenow who pays for care later
Worried about your kids
Keep the cost and the weight of care from landing on your spouse and children.
Worried it goes unused
Some plans pass the value to your family if care is never needed.
Own an annuity or policy
You may be able to add care coverage to an annuity or life policy you already hold.
Spending time in Korea
Some plans pay a cash benefit you can use while living in Korea.
It is closer than it looks
- About 70% of over-65s
- Roughly 70% of Americans over 65 will need long-term care at some point in their lives.
- Over $100,000 a year
- Nursing home care often runs past $100,000 a year. Retirement savings drain faster than most people expect.
- 2 of the 6 ADLs
- Benefits usually begin when you cannot manage 2 of 6 daily activities (bathing, toileting, dressing, transferring, eating, continence) on your own for more than 90 days.
Over-65 figure: U.S. Department of Health and Human Services. Costs and benefit triggers vary by area, facility and product.
Medicare does not cover long-term care
Medicare pays for short-term skilled nursing after a hospital stay, up to 100 days. The long-term help you need when daily life gets hard is not covered, so it falls to your own savings or your family.
How we plan it together
- 01
I listen first
Your savings, your health, your family. Products come after that.
- 02
We compare what is open
From traditional cover to using an annuity or life policy you own, I lay carriers side by side.
- 03
Apply while healthy
Approval depends on health underwriting. Talk it over with your family and take your time.
Questions people ask
Won’t Medicare pay for care?
Medicare covers short-term skilled nursing after a hospital stay, up to 100 days. It does not cover long-term help with daily life, like bathing or dressing.
What if I never need care?
With a traditional policy, the premiums are gone. Asset-based plans built on a life policy or annuity are designed so the value goes to your family if care is never used. Terms differ, so we check each one together.
Can I use it while living in Korea?
Some cash indemnity plans pay benefits while you are living in Korea. The rules differ by product, so I confirm this before you apply.
When do benefits start?
Usually once you cannot manage two of the six daily activities on your own, and after the elimination period has passed. Ninety days is typical, but it varies by product.
When should I look into this?
There is no set age. But approval and premiums depend on health underwriting, so checking while you are healthy gives you the most options.
Related services
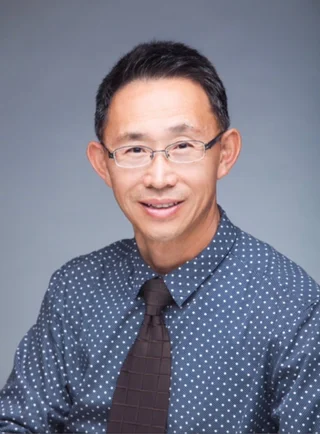
신현인 Sam Shin
Retirement planning specialist · I call you back myself
Book a free call
Leave your name and number and I will get back to you personally.
A call back within one business day
In English or Korean, at a time that suits you.
Carriers compared side by side
The terms on one page, sent to you by email.
-
Free, with no obligation
Tell me you are not interested and I will stop.
Looked after long after you sign
I reach out before maturities and renewals.
Prefer to talk now? (213) 507-2224