Types of annuities
Sort them three ways and the right one shows
Annuities come in many kinds, and each differs in how interest is credited, what it guarantees and how you can use it. Ask three questions: when it pays, what you want from it, and how it’s credited. It gets much simpler.
First call is free · English / 한국어 · CA Lic. #4582405
What an annuitycan do for you
Income for life
Starting now or on a date you choose, for as long as you live.
Principal protection
With principal-protected products, a falling market doesn’t shrink your deposit.
Tax-deferred growth
Tax waits until you withdraw, so more of your money keeps growing.
Passing it on
It goes to your named beneficiary without probate.
1. When does it start paying?
Annuities split in two by when the income begins.
- IMMEDIATE
Immediate annuity
Place a lump sum and income starts within a year, sometimes the next month. It suits people at or already past retirement.
- DEFERRED
Deferred annuity
The money grows or sits for a while, and income begins on a date you choose. It suits people with time before retirement.
2. What do you want from it?
What you most want out of it should decide which product you choose.
- INCOME
Income annuities
The goal is income guaranteed for life. Some keep paying the agreed amount even after the account runs out.
- ACCUMULATION
Growth annuities
The goal is growing your retirement money with tax deferred. The options depend on how much risk you’re comfortable with.
- SPECIAL
Special-purpose
Some annuities strengthen the death benefit or add long-term care coverage.
Growth annuities also include variable annuities, which carry investment risk. I put protecting your principal first, so I focus on products where your deposit is guaranteed.
3. How is interest credited?
How much risk to your principal you can accept decides what fits.
- FIXED
Fixed
The insurer carries the investment risk and credits the rate it agreed. Best when protecting principal matters most.
- MULTI-YEAR
Fixed-rate MYGA
One rate, guaranteed for a set term such as 3, 5 or 7 years.
- INDEX-LINKED
Index annuity (FIA)
Interest is linked to a market index, and your principal is protected when the index falls.
Questions people ask
Is an annuity an investment?
Fixed, MYGA, index and immediate annuities are insurance contracts, backed by the issuing insurer’s claims-paying ability. Variable annuities are investments and can lose principal.
Immediate or deferred: which fits me?
If you’re retired or need income soon, usually an immediate annuity. If retirement is a few years away, usually a deferred one. I’ll compare both against your age and the amount you need.
How is a MYGA different from an index annuity?
A MYGA locks one rate for the term. An index annuity credits interest based on the index, within limits, and gives you 0% instead of a loss in years the index falls.
There are so many. Do you compare them all?
Yes. Carriers differ in how they credit interest, what they guarantee and their rules for use. I’m not tied to one company, so I compare products from several side by side.
Do I have to pick just one?
No. Many people put what they need for living costs into an income annuity and the money they won’t touch for a while into a MYGA or index annuity.
Related services
-
Fixed-rate MYGA
A guaranteed rate that can beat a CD, with tax deferred until you withdraw.
Index annuity
Interest linked to an index in up years, and 0% instead of a loss in down years.
-
Lifetime income
Fill the gap Social Security leaves, every month, for as long as you live.
Immediate annuity (SPIA)
Place a lump sum, and income can start as soon as next month, for life.
Annuity buying guide
Goal, comparison, conditions, decision: four steps, in order.
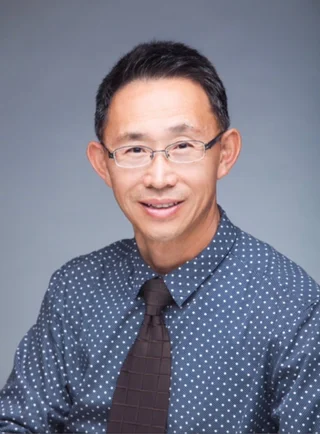
신현인 Sam Shin
Retirement planning specialist · I call you back myself
Book a free call
Leave your name and number and I will get back to you personally.
A call back within one business day
In English or Korean, at a time that suits you.
-
Carriers compared side by side
The terms on one page, sent to you by email.
-
Free, with no obligation
Tell me you are not interested and I will stop.
Looked after long after you sign
I reach out before maturities and renewals.
Prefer to talk now? (213) 507-2224