Annuity buying guide
Don’t choose on the rate alone
Annuities vary widely in type and features. So you don’t decide on a headline rate alone, here’s the order to work through. Set the goal, compare, check the conditions, then decide.
First call is free · English / 한국어 · CA Lic. #4582405
Before you choose,think about this
If you want growth
Steadily with tax deferral, or a little more with index-linked interest.
If you need income
With an income rider, the agreed amount continues even if the account runs dry.
If principal comes first
Focus on principal-protected options: fixed, MYGA and index.
How long can it sit?
Make sure you won’t need the money during the surrender period.
Four steps, in order
- 01
Set the goal
Decide first whether this money is for growth or for lifetime income.
- 02
Compare carriers
The same type of annuity can differ in rate, cost, bonus and payout terms.
- 03
Look underneath
Look past the projection chart to the conditions, withdrawal limits especially.
- 04
Decide in your own time
Take the time to talk it over with your family. There’s no rush.
Six things to check
-
Surrender charges
Ending the contract before the term is up costs you.
-
Ongoing cost
Fixed products usually carry none, but riders such as lifetime income do have a cost.
-
The carrier’s strength
Check ratings from AM Best or S&P. A guarantee is only as strong as the company behind it.
-
How the bonus works
Find out whether a bonus adds to your cash value or only to the figure used to calculate income.
-
The free-look window
Usually 10 to 30 days after purchase when you can cancel without penalty.
-
The contract itself
Before you sign, we confirm together that the contract says what you were told.
Terms vary by state and product. I lay them out product by product in your comparison.
On your side of the table, not one carrier’s
An annuity is a long-term decision. I’m not tied to one carrier, so I line up products from several companies side by side. A consultation never obliges you to buy.
Questions people ask
Is the highest rate the best product?
Not necessarily. The surrender period, withdrawal limits, bonus terms and the carrier’s rating all decide whether it actually works in your favor.
How do I check a carrier’s rating?
Agencies such as AM Best and S&P rate insurers’ financial strength. I include the ratings in your comparison.
What if I change my mind after buying?
During the free-look period, usually 10 to 30 days, you can cancel without penalty. The length varies by state and product, and I’ll tell you yours when you sign.
Are all bonuses the same?
No. Some add to your cash value; others only count toward the income calculation, and some lengthen the surrender period. I’ll show you which kind it is up front.
If I meet with you, do I have to buy?
No. My job is to put your situation in order and show you the options. Talk it over with your family first. There’s no rush.
Related services
Fixed-rate MYGA
A guaranteed rate that can beat a CD, with tax deferred until you withdraw.
-
Index annuity
Interest linked to an index in up years, and 0% instead of a loss in down years.
-
Lifetime income
Fill the gap Social Security leaves, every month, for as long as you live.
Immediate annuity (SPIA)
Place a lump sum, and income can start as soon as next month, for life.
Types of annuities
Sorted by when it pays, what it’s for and how interest is credited.
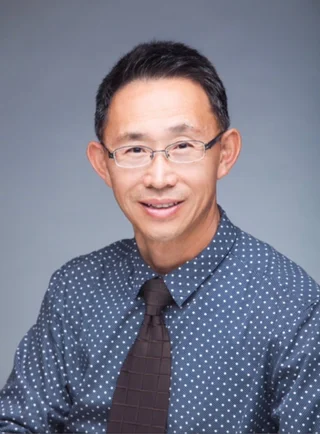
신현인 Sam Shin
Retirement planning specialist · I call you back myself
Book a free call
Leave your name and number and I will get back to you personally.
A call back within one business day
In English or Korean, at a time that suits you.
-
Carriers compared side by side
The terms on one page, sent to you by email.
-
Free, with no obligation
Tell me you are not interested and I will stop.
-
Looked after long after you sign
I reach out before maturities and renewals.
Prefer to talk now? (213) 507-2224