Index annuity (FIA)
Up with the index, 0% when it falls
In years the index (such as the S&P 500) rises, you’re credited interest up to a limit. In years it falls, you get 0% and your principal stays whole. Interest grows tax-deferred.
First call is free · English / 한국어 · CA Lic. #4582405
Protect the principal,and hope for a bit more
More, without the losses
In a down year you get 0%. Your principal doesn’t shrink.
A CD or MYGA feels thin
Aim for a better result than a fixed rate.
Money for 7–10 years
Grow it over the medium term while protecting the principal.
Income later, too
You can add a lifetime income rider.
How it works
- 01
Choose an index and method
I compare indexes like the S&P 500 and cap or participation designs.
- 02
Up years add interest
Index gains are credited as interest, up to the set limit.
- 03
Down years are 0%
Your principal and the interest already credited stay put.
How it differs from a MYGA
- Interest
- Fixed-rate MYGA A set rate for the whole termIndex annuity Based on the index, within set limits
- Down years
- Fixed-rate MYGA Not applicableIndex annuity 0% credited; principal and past interest kept
- Best for
- Fixed-rate MYGA People who want the number fixed up frontIndex annuity Principal protection with room for more
- Taxes
- Fixed-rate MYGA Deferred until you withdrawIndex annuity Deferred until you withdraw
| Fixed-rate MYGA | Index annuity | |
|---|---|---|
| Interest | A set rate for the whole term | Based on the index, within set limits |
| Down years | Not applicable | 0% credited; principal and past interest kept |
| Best for | People who want the number fixed up front | Principal protection with room for more |
| Taxes | Deferred until you withdraw | Deferred until you withdraw |
The S&P 500® is a product of S&P Dow Jones Indices LLC. Index annuities are not sponsored, endorsed, sold or promoted by SPDJI, Dow Jones or S&P.
Questions people ask
Can I lose money?
The 0% floor means a down year doesn’t reduce your principal or credited interest. Surrendering early, or rider fees larger than the interest credited, can still reduce the value.
What are caps, participation rates and spreads?
If the index rises 10%, a product with an 8% cap credits 8%, a 70% participation rate credits 7%, and a 2% spread credits 8%. How interest is captured matters more than any single number.
Is a bonus really a bonus?
Some bonuses add to your cash value; others only count toward the income calculation. Some also lengthen the surrender period. I’ll show you which kind it is up front.
Is my money invested in stocks?
No. It’s an insurance contract, and the index is only used to calculate interest. Dividends aren’t included.
Are there costs?
The base contract usually has none. Optional riders, such as lifetime income or enhanced caps, carry an annual cost.
Related services
-
Fixed-rate MYGA
A guaranteed rate that can beat a CD, with tax deferred until you withdraw.
-
Lifetime income
Fill the gap Social Security leaves, every month, for as long as you live.
Immediate annuity (SPIA)
Place a lump sum, and income can start as soon as next month, for life.
Types of annuities
Sorted by when it pays, what it’s for and how interest is credited.
Annuity buying guide
Goal, comparison, conditions, decision: four steps, in order.
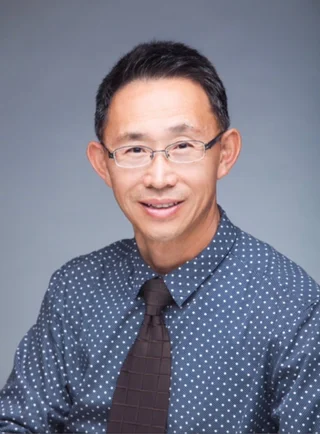
신현인 Sam Shin
Retirement planning specialist · I call you back myself
Book a free call
Leave your name and number and I will get back to you personally.
A call back within one business day
In English or Korean, at a time that suits you.
-
Carriers compared side by side
The terms on one page, sent to you by email.
-
Free, with no obligation
Tell me you are not interested and I will stop.
-
Looked after long after you sign
I reach out before maturities and renewals.
Prefer to talk now? (213) 507-2224