Lifetime income annuity
A retirement paycheck for as long as you live
Social Security covers part of your living costs. Fill the rest with a lifetime income annuity, and a payment arrives every month, whatever the market does and however long you live.
First call is free · English / 한국어 · CA Lic. #4582405
For anyone who needsa monthly paycheck in retirement
Short of monthly income
Fill the gap in your living costs, every month.
Afraid of outliving it
Live longer than your savings and the payments continue.
Worried about a downturn
If the market falls, your payment stays the same.
Income for both of you
With a joint payout, both of you are paid for life.
How it works
- 01
Find the gap
Take your living costs, subtract Social Security, and set the monthly amount you need.
- 02
Choose the approach
Compare a deferred annuity with an income rider against an immediate annuity (SPIA).
- 03
Start the paychecks
From the age you pick, for life, even after the contract value runs out.
Two ways to get there
- Starts
- Immediate annuity (SPIA) As soon as next monthDeferred + income rider In a few years, at the age you choose
- Income amount
- Immediate annuity (SPIA) Set when you buyDeferred + income rider Grows the longer you wait
- Money left over
- Immediate annuity (SPIA) Only with a refund or period-certain optionDeferred + income rider Remaining value goes to your beneficiaries
- Best for
- Immediate annuity (SPIA) Retired now or about to beDeferred + income rider A few years from retirement
| Immediate annuity (SPIA) | Deferred + income rider | |
|---|---|---|
| Starts | As soon as next month | In a few years, at the age you choose |
| Income amount | Set when you buy | Grows the longer you wait |
| Money left over | Only with a refund or period-certain option | Remaining value goes to your beneficiaries |
| Best for | Retired now or about to be | A few years from retirement |
Questions people ask
If I die early, does the insurer keep everything?
With a rider, any remaining contract value goes to your beneficiaries. With an immediate annuity, choose a refund or period-certain option.
What does the rider cost?
Usually around 1% a year, deducted from the contract value; the guaranteed income amount doesn’t go down. I’ll also compare products with no rider fee.
Is it really for life?
Yes. It’s written into the contract and keeps paying after the contract value is used up, backed by the issuing insurer’s claims-paying ability.
Can my spouse be covered too?
Choose a joint payout. The amount is a little lower, but it keeps paying the surviving spouse.
Does starting later mean more income?
Usually, yes. Each carrier calculates it differently, so which one comes out ahead depends on when you start.
Related services
Fixed-rate MYGA
A guaranteed rate that can beat a CD, with tax deferred until you withdraw.
Index annuity
Interest linked to an index in up years, and 0% instead of a loss in down years.
Immediate annuity (SPIA)
Place a lump sum, and income can start as soon as next month, for life.
-
Types of annuities
Sorted by when it pays, what it’s for and how interest is credited.
Annuity buying guide
Goal, comparison, conditions, decision: four steps, in order.
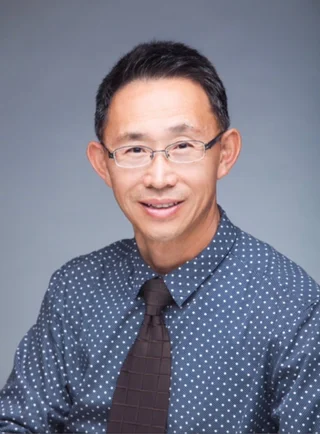
신현인 Sam Shin
Retirement planning specialist · I call you back myself
Book a free call
Leave your name and number and I will get back to you personally.
A call back within one business day
In English or Korean, at a time that suits you.
-
Carriers compared side by side
The terms on one page, sent to you by email.
-
Free, with no obligation
Tell me you are not interested and I will stop.
Looked after long after you sign
I reach out before maturities and renewals.
Prefer to talk now? (213) 507-2224